When shopping for car insurance, it’s tempting to focus only on the monthly premium. After all, if one company is offering a policy for $75 per month and another is $110, the cheaper one feels like the smarter choice. But in reality, that bargain policy could leave you financially exposed if you’re in an accident.
State Minimums: Just Enough to Be Legal, Not Enough to Be Safe
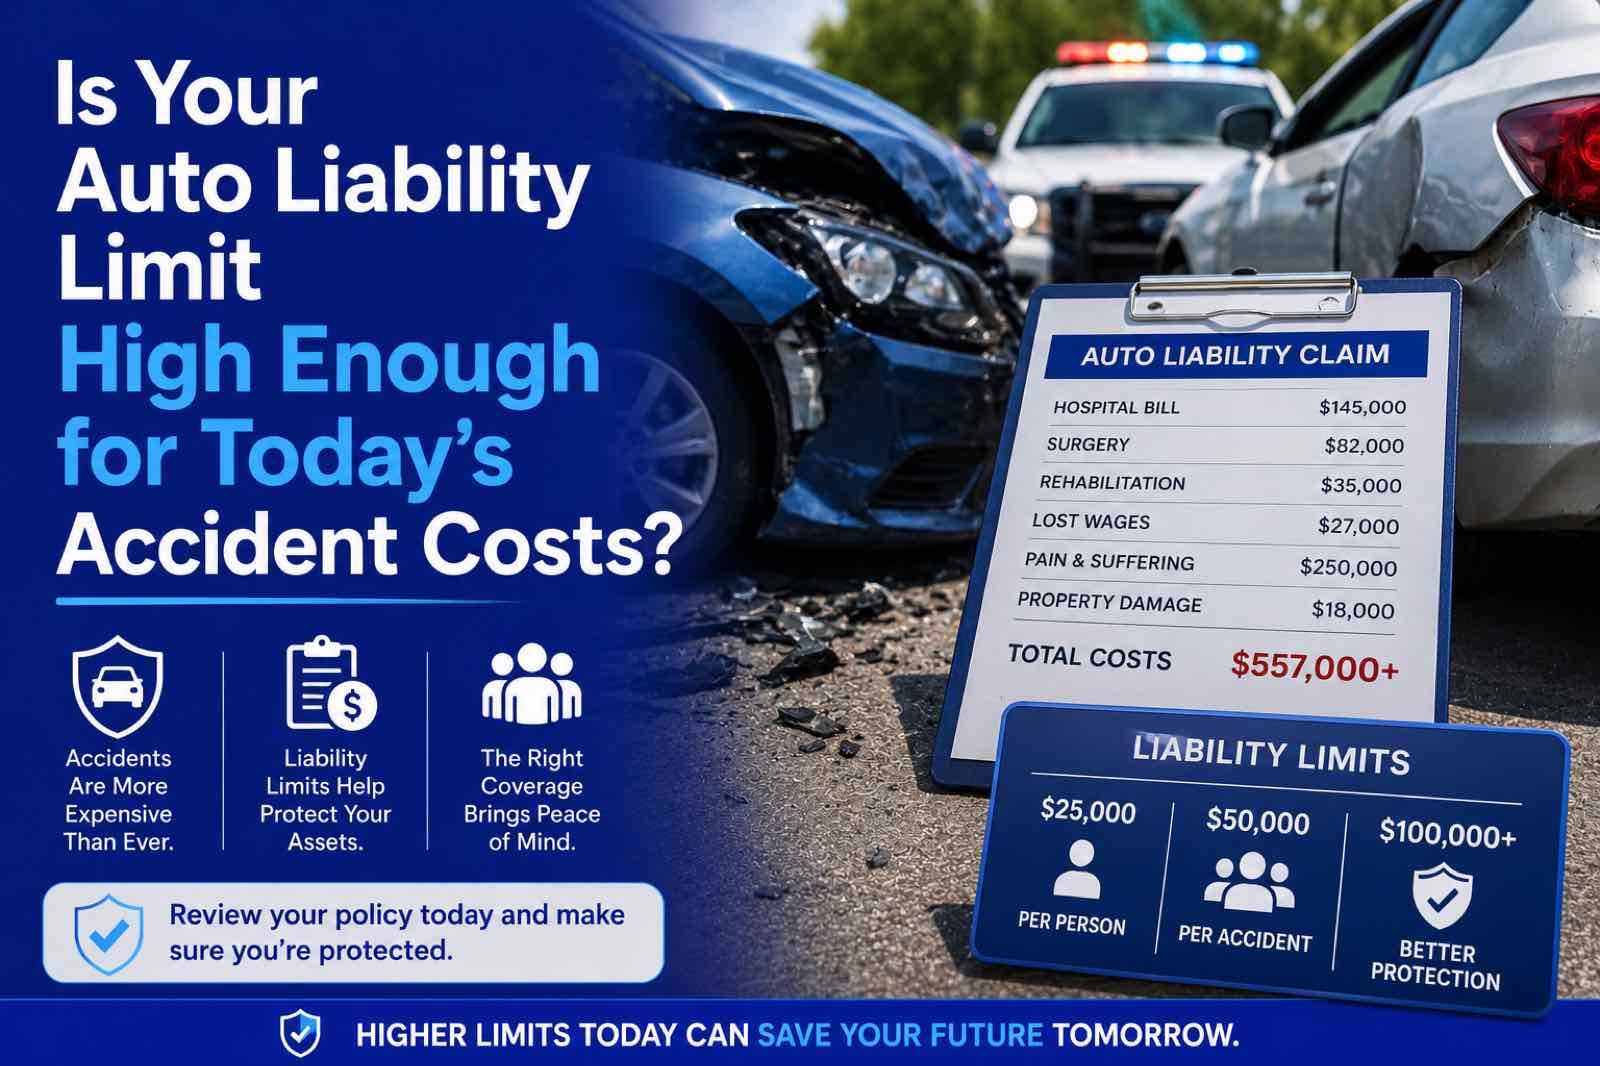
Oklahoma law requires drivers to carry a minimum of $25,000 per person / $50,000 per accident in bodily injury liability, and $25,000 for property damage. Those numbers haven’t kept pace with today’s medical or vehicle repair costs.
- A night in the ER plus follow-up treatment can easily exceed $25,000.
- If you cause a multi-car accident, $25,000 won’t come close to covering damages.
- New trucks, SUVs, and EVs can easily cost $50,000–$70,000. That means one accident could leave you responsible for tens of thousands out-of-pocket.
The state minimum keeps you “street legal,” but it won’t protect your assets if you’re sued.
The Uninsured Driver Problem in Oklahoma
Here’s a scary fact: Oklahoma consistently ranks among the top states for uninsured drivers, with estimates of nearly 1 in 4 cars on the road being uninsured. If you get hit by one of these drivers, your medical bills and lost wages could fall on you — unless you carry Uninsured/Underinsured Motorist (UM/UIM) coverage.
Yet many “cheapest” auto insurance policies either exclude UM/UIM coverage or sell it as an add-on. Cutting it out might save a few dollars a month, but it leaves you vulnerable to one of the most common real-world risks in Oklahoma.
Comprehensive Protection vs. Rock-Bottom Pricing
Cheap policies often reduce coverage by:
- Raising deductibles so high that you can’t afford to use your insurance.
- Excluding coverage for rental reimbursement or roadside assistance.
- Skipping UM/UIM altogether.
When you talk to us, we will show you a balance between affordable premiums and meaningful coverage. Sometimes the difference between a rock-bottom policy and a well-rounded one is less than the cost of a cup of coffee per week.
Bottom line: Don’t just ask “what’s the cheapest?” Ask “what protects me best if the worst happens?”
Stay Tuned For Other Great Reads In This Month’s Newsletter
- Homeowners Ins in Oklahoma — What’s Actually Covered (and What’s Not)
- Why Renters Insurance is a Must in Oklahoma (Even if You Don’t Own a Home)
Connect with us Oklahoma Insurance Group