It’s one of the questions we hear most at renewal: “My car is another year older and worth less. Why did my auto insurance go up?”
It’s a fair question, and the answer starts with what you’re actually paying for.
Most of your premium isn’t about your car
Pull out your declarations page and look at the coverages listed. A typical Oklahoma auto policy includes some combination of:
- Bodily injury liability
- Property damage liability
- Uninsured motorist
- Underinsured motorist
- Medical payments
- Rental reimbursement
- Comprehensive and collision
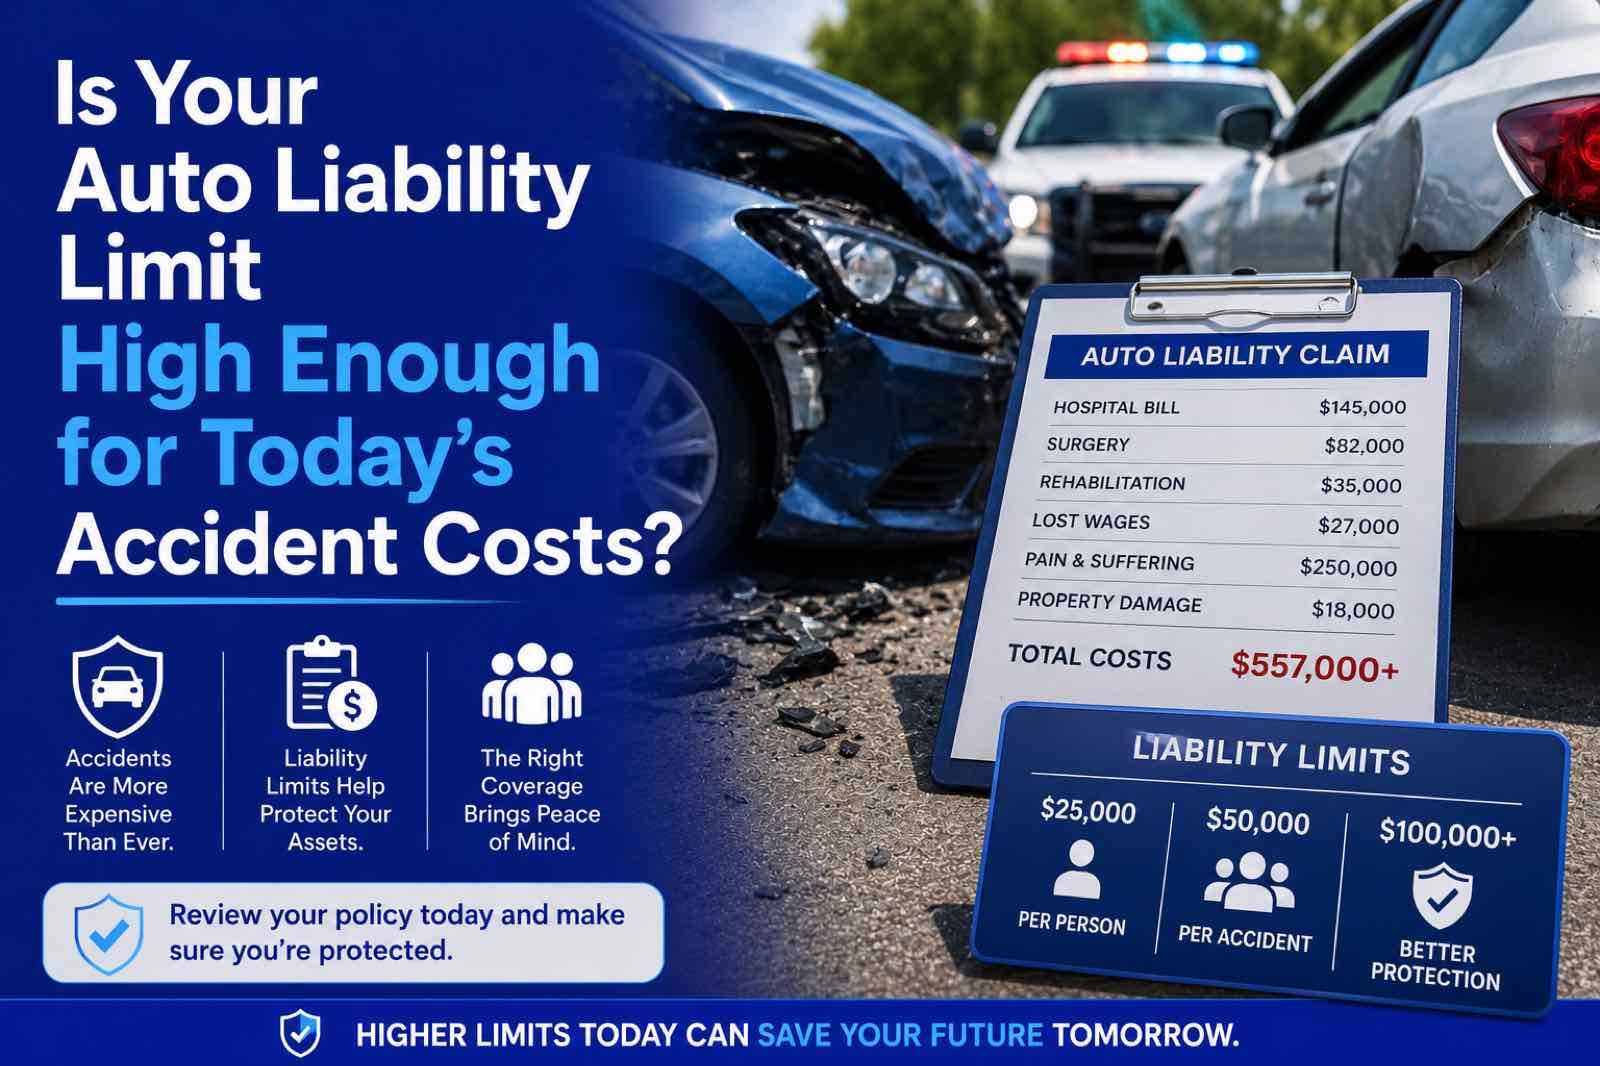
Only the last line, comprehensive and collision, is really about your car. Everything above it covers people: the people you might hurt, the property you might damage, and you and your passengers if the other driver can’t pay. Each one has its own price on the page.
So as your car gets older, the comprehensive and collision portion may come down. The rest of the premium follows the cost of what it pays for, and those costs keep climbing. Medical bills, attorney involvement and the price of repairing someone else’s late-model car all rise year after year, whatever your own car is worth.
You’re priced as part of a bigger group
Your rate is also shaped by everyone else your carrier insures. Insurance works by spreading losses across a large pool of drivers. When that pool has more accidents, more expensive repairs or more lawsuits (and Oklahoma has had its share of hail, wrecks and rising repair costs), carriers file rate increases across the board, even for drivers who haven’t had a claim.
Oklahoma also has one of the higher rates of uninsured drivers in the country, which makes uninsured motorist coverage more important and more expensive to provide.
What you can do about it
You can’t control the market, but you can control how your policy is set up:
- Look at the whole page, not just the total. Make sure you’re paying for coverages that still fit your situation.
- Revisit comprehensive and collision on an older car. If the car is paid off and worth little, the math may favor dropping or raising the deductible on those, but talk it through first.
- Shop it. Carriers raise rates at different times and by different amounts. As an independent agency, we can put your policy in front of several of them at renewal.
If your premium jumped and you want to know why, send us your declarations page and we’ll go through it with you line by line.