Ask anyone who’s owned a rental house around Norman or the OKC metro and most will tell you the same thing: it was more work and more money than they planned on. Rentals can absolutely pay off. But from where we sit, insuring a lot of them, we see the same handful of mistakes turn a good investment into a headache.
None of us at Oklahoma Insurance Group are property managers. What we do see is every rental claim, every policy that gets declined, and every landlord who finds out too late they had the wrong coverage. These are the five rules we’d give a friend buying their first rental.
1. Know the house before you buy it
The cheapest house on the market is usually cheap for a reason. Older wiring, tired plumbing, a furnace past its life, a roof that’s taken too many Oklahoma hailstorms: those are exactly the things that make a carrier hesitate to write a rental, and the things that turn into claims once a tenant moves in.
Be especially careful with “as-is” houses. Most are foreclosures or homes that sat empty, and the repair bill almost always runs past the estimate.
Before you buy:
- Hire an independent home inspector and read the whole report.
- Look hard at the wiring, plumbing, heating and roof. Carriers ask how old each one is, and anything not updated in the last 10 to 15 years can limit your options or raise the price.
- Bring it up to code before a tenant moves in. If something’s wrong and a tenant gets hurt, that’s a liability claim with your name on it.
- Test for mold and keep the results. Don’t assume it isn’t there.
Sometimes the right answer is to walk away from a house that would cost too much to fix. That’s your call, but make it before you close, not after.
2. Put everything in a written lease
“You break it, you buy it” isn’t a lease. Pay an attorney to draft a written lease you can use on every property, aim for 12-month terms where you can, and walk each tenant through it before they sign. A clear lease saves you time and money when something goes wrong, and it tells the tenant you take the property seriously.
3. Screen every tenant
Most landlords we talk to are in a hurry to get rent coming in, and screening gets skipped. Run credit and background checks; they’re inexpensive and they’re the best predictor you have.
Then make renters insurance a lease requirement. Your landlord policy covers your building, not your tenant’s belongings or their liability. A tenant with no coverage who loses everything in a fire is a tenant who can’t pay rent, and if their mistake starts that fire, their renters liability coverage gives you and your carrier someone to recover the damage from.
Pets and smoking are your decision, but think about both. Dog bites and house fires are two of the more expensive liability claims a rental can produce.
4. Insure it as a rental, not as a home
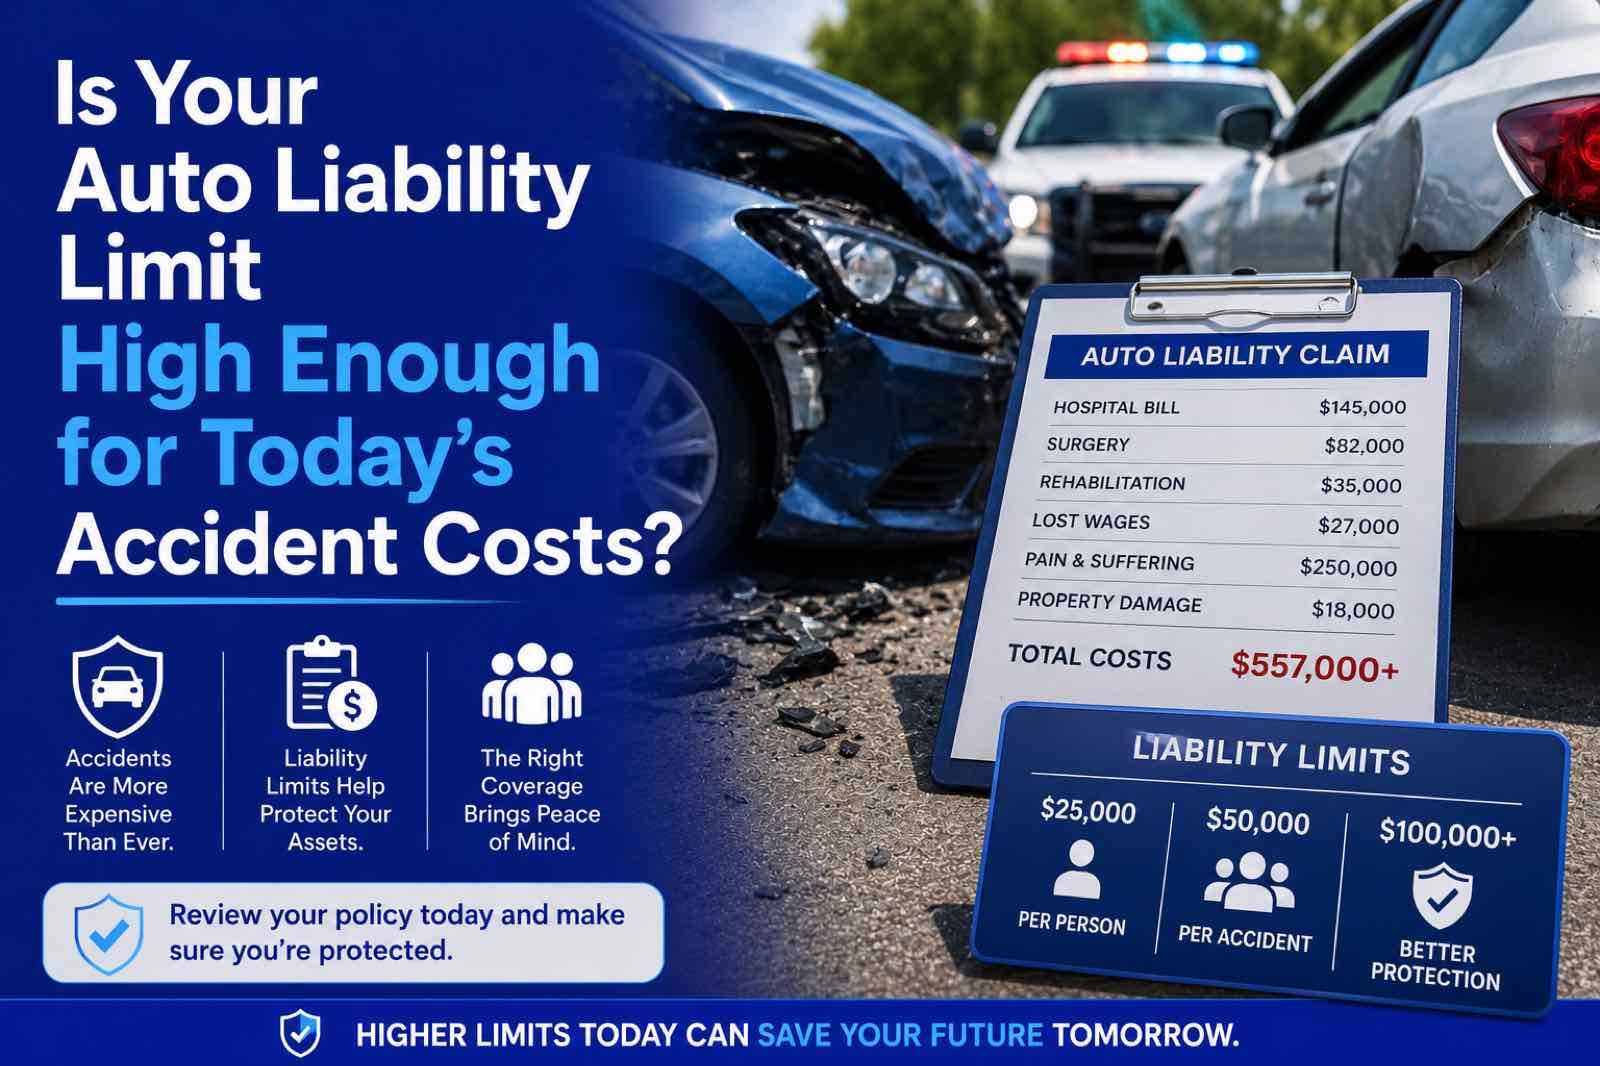
This is the one that costs people the most. A homeowners policy is not written for a house you don’t live in. If your tenant’s house burns and it’s insured on a homeowners form, expect a hard conversation with the claims adjuster.
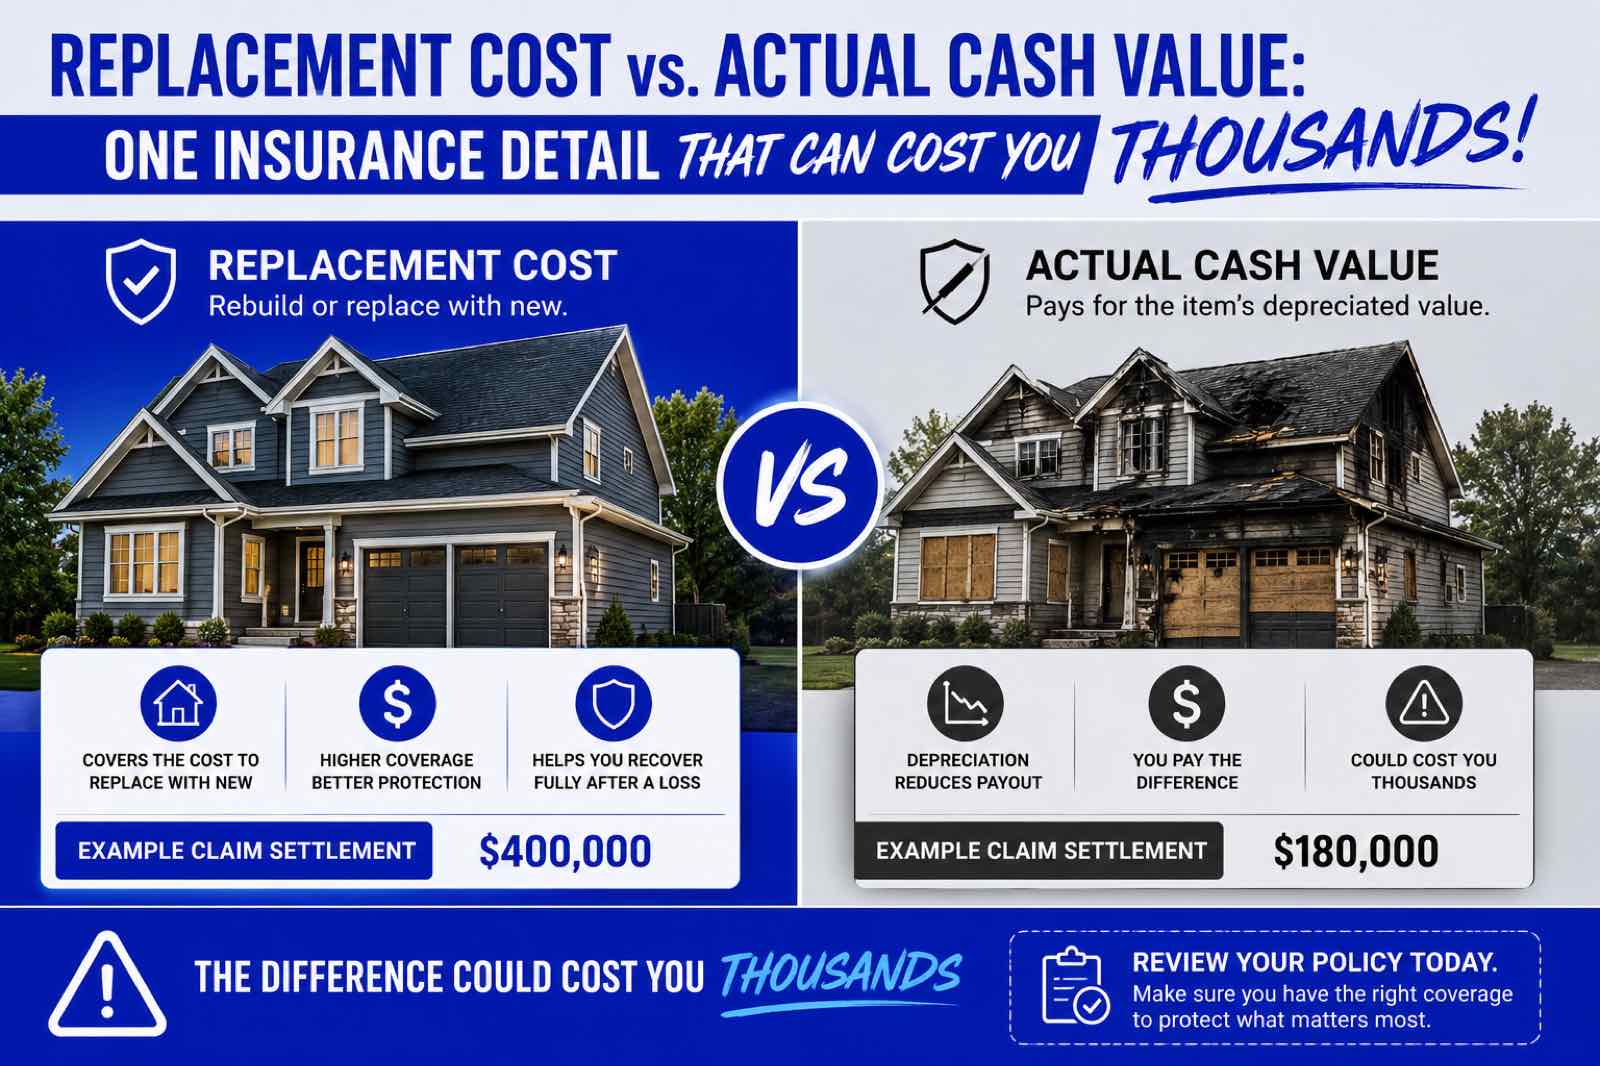
A rental needs a dwelling fire or landlord policy. Underwriting is usually a little stricter than homeowners and the coverage is built differently, so it’s worth going through line by line: the dwelling limit, loss of rents if the house can’t be lived in after a claim, and premises liability, which often has to be added to a landlord policy rather than coming with it.
Watch vacancy, too. Most landlord policies cut back or drop coverage once a house sits empty for 30 or 60 straight days. If you know it’ll be vacant between tenants or during a remodel, call us before that clock runs out. There are policies written for vacant houses, but you need to switch to one in time.
5. Keep tabs on the property
When a landlord calls us for a quote, we ask about the house: brick or siding, how old the roof is, when the heat and air were replaced. A surprising number of owners don’t know. We’ve even had people try to insure a flipped house they’d never set foot in.
Know your property. Keep a file of every repair, drive by every few months, and take care of it the way you would your own home. It protects the investment, and it makes the house easier to insure at a fair price.
Do those five things and a rental has a much better chance of being the income you bought it for. If you own a rental, or you’re about to buy one, give us a call and we’ll make sure it’s insured as one.